StratEvo MCP Server
io.github.NeuZhou/stratevo
Evolve trading strategies using genetic algorithms across 484+ market factors with walk-forward validation.
What is the StratEvo MCP server?
StratEvo is a genetic algorithm engine that automatically discovers and evolves trading strategies by breeding candidate DNA across 484+ market factors and validating them through walk-forward testing. It eliminates manual strategy writing by using evolutionary computation to optimize factor weights, position sizing, and risk parameters across US stocks and crypto markets.
StratEvo automates quantitative trading strategy discovery through genetic algorithms. Instead of manually writing and tuning strategies, you define the rules and let the engine evolve optimal factor weights and parameters across multiple market windows. It includes walk-forward validation, Monte Carlo robustness testing, paper trading, and real-time signal generation to prevent overfitting and prove strategies work on unseen data.
How to install StratEvo
Copy-paste configuration for popular MCP clients.
Tools & capabilities
Tools this server exposes to the agent.
Genetic Algorithm Strategy Evolution— Breeds and mutates trading strategy DNA across 484+ factors with fitness selection based on Sharpe ratio, returns, and drawdown.Walk-Forward Validation— Multi-window out-of-sample backtesting to ensure strategies generalize beyond training data.Monte Carlo Simulation— 1,000 shuffled iterations with p-value testing to distinguish signal from luck.Paper Trading— Forward-testing evolved strategies on real market data with simulated execution and daily P&L reporting.Live Signal Generation— Real-time buy/sell signals from evolved strategies updated daily with git-committed history.Factor Library— 484+ evolvable factors across crypto-native, momentum, volume, volatility, mean reversion, trend following, and other categories.Backtesting Engine— Simulates strategy execution with real fees, slippage, and position caps across US stocks and crypto markets.
Use cases
- Discover profitable trading strategies without manually writing rules or tuning parameters
- Validate that evolved strategies generalize to unseen market data using walk-forward and Monte Carlo testing
- Generate daily buy/sell signals from evolved strategies for US stocks and crypto assets
- Compare multiple evolved strategy styles (momentum, mean reversion, flow reading, volatility hunting) on the same market
- Optimize position sizing and risk parameters (trailing stops, Kelly fraction, market regime sensitivity) automatically through evolution
StratEvo MCP server FAQ
StratEvo uses genetic algorithms to automatically discover trading strategies by evolving factor weights and parameters, rather than requiring you to manually write and tune them. It includes walk-forward validation and Monte Carlo testing to prevent overfitting.
StratEvo is available via PyPI, but StratEvo Pro (the full evolution engine, paper trading, and live exchange connectors) requires contact with the developer at neuzhou@outlook.com for access and pricing.
StratEvo supports US stocks (S&P 500) and cryptocurrency assets, with 484+ evolvable factors including crypto-native indicators like funding rates and whale detection.
It uses walk-forward validation across multiple time windows, Monte Carlo simulation with 1,000 shuffled iterations, combinatorial purged cross-validation, and automatic bias detection for look-ahead and survivorship bias.
StratEvo is available as an MCP server via PyPI (stratevo) and can be integrated into Cursor or Claude through the standard MCP connection methods.
US Stocks V8 shows 33.5% annual return with 1.47 Sharpe ratio; Crypto V13 shows 69.0% annual return with 2.27 Sharpe ratio. These are walk-forward validated backtests, with paper trading results accumulating since April 2026.
README (reference)
Source of truth, from the repository.
🦀 StratEvo
Stop writing trading strategies. Evolve them.
A genetic algorithm engine that breeds and walk-forward validates trading strategies across 484+ market factors.
<p align="center"> <img src="https://img.shields.io/badge/evolvable_factors-484+-orange" alt="484+ Evolvable Factors"> <img src="https://img.shields.io/badge/markets-US_Stocks_%7C_Crypto-blue" alt="Markets"> <img src="https://img.shields.io/badge/validation-Walk--Forward_%7C_Monte_Carlo-green" alt="Validation"> <a href="https://discord.gg/kAQD7Cj8"><img src="https://img.shields.io/discord/1488800950696284272?color=7289da&label=Discord&logo=discord&logoColor=white" alt="Discord"></a> </p> <p> <a href="#-live-signals">Live Signals</a> · <a href="#-paper-trading-performance">Paper Trading</a> · <a href="#how-it-works">How It Works</a> · <a href="#evolution-results">Results</a> · <a href="#anti-overfitting">Robustness</a> · <a href="#get-access">Get Access</a> </p> </div>📡 Live Signals
Real-time buy/sell signals from evolved strategies. Updated daily. All signals are committed to git history — you can verify every one.
Latest Signals
<!-- SIGNALS_START -->| Date | Market | Action | Asset | Entry Price | DNA | Status |
|---|---|---|---|---|---|---|
| Signals will be posted here as Paper Trading goes live |
📁 Full signal history: signals/
📊 Paper Trading Performance
Forward-testing evolved strategies on real market data with simulated execution. No hindsight, no cherry-picking.
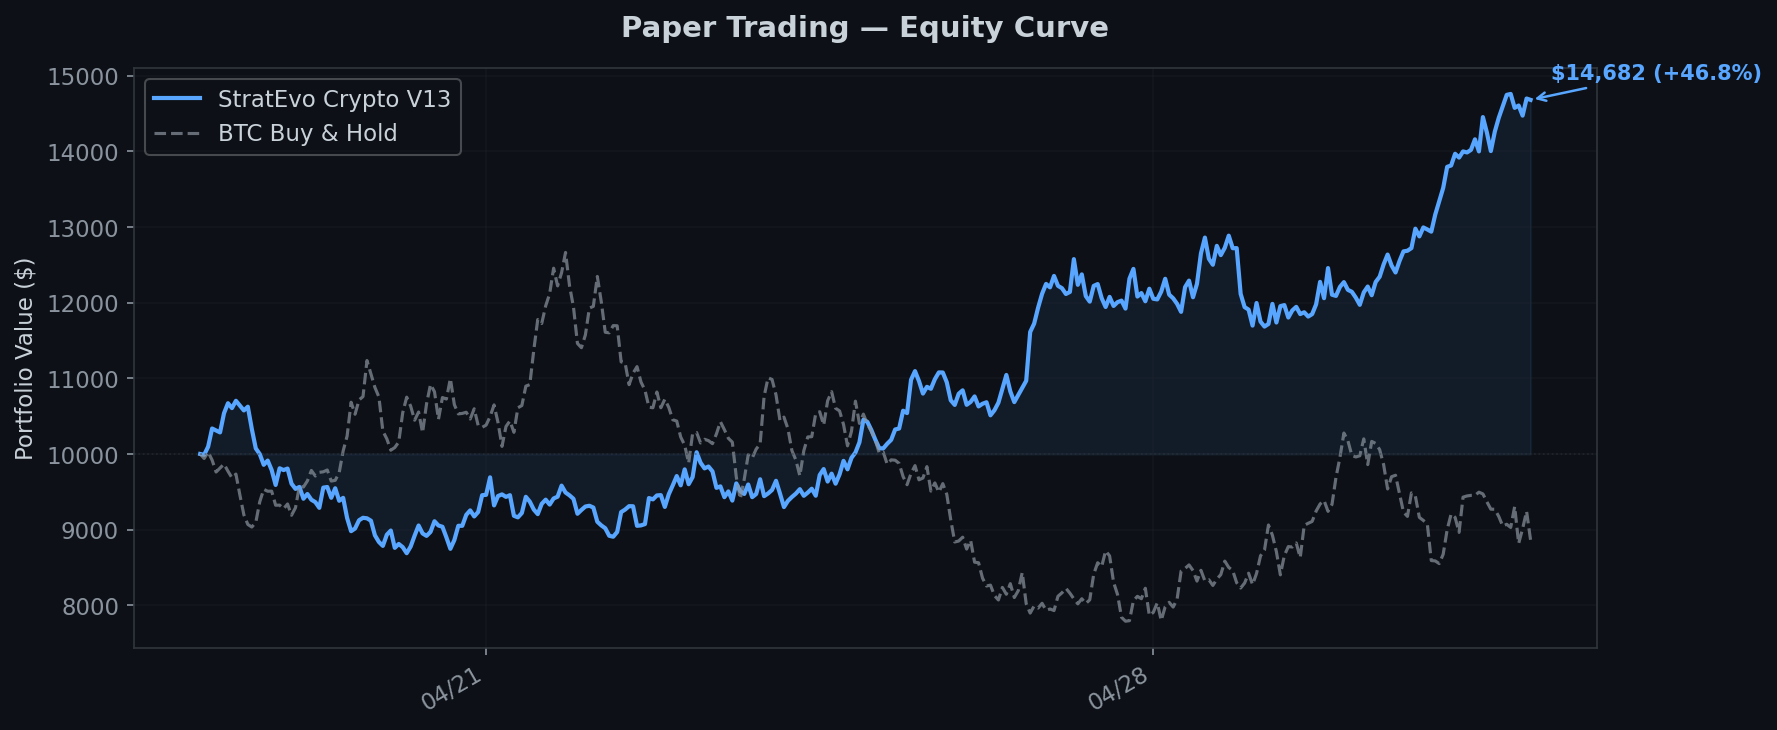
Paper Trading active — Crypto V13 live since 2026-04-18.
Current Paper Portfolio
<!-- PAPER_START -->| Strategy | Market | Start Date | Days | Return | Sharpe | MaxDD | Trades | Status |
|---|---|---|---|---|---|---|---|---|
| Crypto V13 | Crypto | 2026-04-18 | 0 | — | — | — | — | 🟢 Live |
📁 Daily P&L reports: paper-trading/
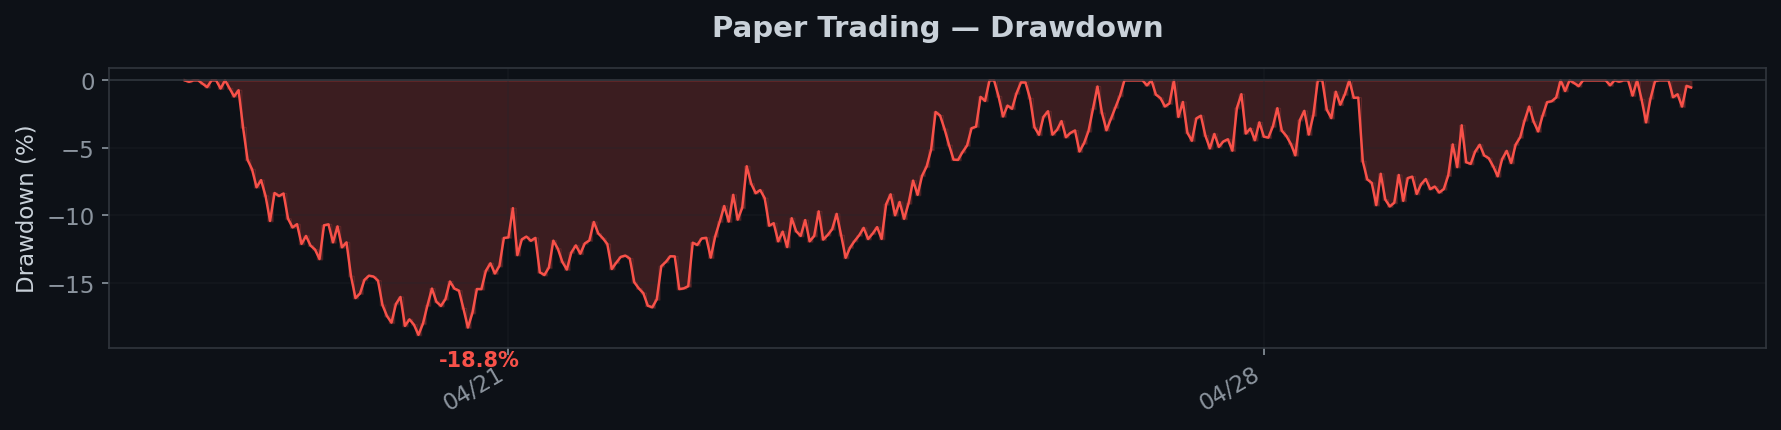
📈 Equity curves: paper-trading/charts/
Equity Curve (demo — real data accumulating)
Drawdown
How It Works
Most quant tools make you write the strategy. StratEvo evolves them instead.
You write the rules        →  StratEvo discovers the rules
You tune parameters        →  GA tunes parameters
You test on one period     →  Walk-forward tests on multiple windows
You hope it generalizes    →  Monte Carlo measures if it does
  Random DNA population (484 factor weights + risk parameters)
       │
       ▼
  ┌──────────────────────┐
  │  Walk-Forward Test   │  Multi-window out-of-sample validation
  │  each DNA candidate  │  Real fees, slippage, position caps
  └──────────┬───────────┘
             │
             ▼
  Keep the survivors (fitness = Sharpe × Return / MaxDD)
             │
             ▼
  Mutate + Crossover → next generation
             │
             ▼
  Repeat for N generations
Each DNA is a weight vector across 484+ factors plus risk/position parameters — all evolvable:
| Parameter | Range | What it controls |
|---|---|---|
| Factor weights (×484) | 0.0–1.0 | Which factors matter and how much |
hold_days | 2–60 | Day trades through swing trades |
trailing_stop | % | Trail below peak to lock in profits |
market_regime | sensitivity | Reduce exposure automatically in bear markets |
kelly_fraction | 0–1 | Position sizing from recent win rate |
Evolution Results
Numbers from our running evolution engines. Updated as generations progress.
🇺🇸 US Stocks V8 (100 S&P 500 stocks — Gen 136)
| Metric | Best DNA |
|---|---|
| Annual Return | 33.5% |
| Sharpe Ratio | 1.47 |
| Max Drawdown | 17.0% |
| Win Rate | 55.5% |
| Profit Factor | 1.75 |
| Total Trades | 179 |
₿ Crypto V13 (17 assets — Gen 53)
| Metric | Best DNA |
|---|---|
| Annual Return | 69.0% |
| Sharpe Ratio | 2.27 |
| Max Drawdown | 13.0% |
| Win Rate | 50.0% |
| Profit Factor | 1.58 |
| Total Trades | 174 |
These are backtests with walk-forward validation, not live trades. That's the whole point of paper trading — proving it works forward, not just backward.
Anti-Overfitting
We learned this the hard way. An early version showed 25,000% returns. Turned out to be a bug — look-ahead bias.
| Defense | What it does |
|---|---|
| Walk-Forward | Multi-window OOS validation. Must profit on data it never trained on. |
| Monte Carlo | 1,000 shuffled iterations. p-value < 0.05 or it's luck. |
| CPCV | Combinatorial Purged Cross-Validation. Industry standard for a reason. |
| Arena Mode | Multiple strategies compete head-to-head. Crowded signals get penalized. |
| Bias Detection | Look-ahead, snooping, survivorship — flagged automatically. |
| Turnover Penalty | Excessive trading is punished. Real transaction costs baked in. |
An honest 33% beats a fake 25,000%.
484+ Factors
| Category | Count | Examples |
|---|---|---|
| Crypto-Native | 200 | Funding rate, whale detection, liquidation cascade |
| Momentum | 14 | ROC, acceleration, trend strength |
| Volume & Flow | 13 | OBV, smart money, Wyckoff VSA |
| Volatility | 13 | ATR, Bollinger squeeze, vol-of-vol |
| Mean Reversion | 12 | Z-score, Keltner channel position |
| Trend Following | 14 | ADX, EMA golden cross, MA fan |
| Qlib Alpha158 | 11 | Microsoft Qlib compatible factors |
| + 5 more categories | 37 | Risk, quality, price structure, sentiment, DRL |
All factor weights are discovered by evolution. Zero manual tuning.
Strategy Styles
The algorithm converges on recognizable trading styles on its own:
| Style | What the DNA learned |
|---|---|
| Value Seeker | Buys cheap, holds patient |
| Momentum Rider | Chases runners, dumps laggards |
| Mean Reverter | Bets on bounce-backs |
| Flow Reader | Follows the money — volume leads price |
| Volatility Hunter | Profits from vol expansion |
| Crypto Native | 200 factors built for 24/7 markets |
Get Access
StratEvo Pro includes the evolution engine, paper trading, signal generation, and live exchange connectors.
📧 Contact: neuzhou@outlook.com
💬 Discord: discord.gg/kAQD7Cj8
Technical Papers
<div align="center">
Check back daily for updated signals and paper trading results.
</div>Related MCP servers
Deterministic same-seed but-for twin for battery fleets — synthetic-only (DR-236)

Bright Security
AI-powered application security testing — scan APIs, discover endpoints, and find vulnerabilities.

Ephemeral 7-day hybrid vector+BM25 working memory, multilingual, backed by Redis Stack.


Agent Droid Bridge
AI agents control Android devices and emulators via ADB for mobile automation, testing, and analysis.

Wrap any korg:introspect@v1-aware binary as a Claude Code tool, honoring declared side-effects.